Article - September 14, 2021
Pharmaceutical companies are seeking efficiency in drug development and higher returns on approved therapies. In this quest, they are increasingly turning to outsourcers to help them drive efficiency across their value chains. That`s why outsourced pharmaceutical services growth is accelerating, from drug discovery, contract research, and contract manufacturing to commercialization services, safety and risk management, and pharmaceutical IT. (See our Return on Innovation Series)
In this article, professionals from the Harris Williams Healthcare & Life Sciences Group discuss contract development and manufacturing, a segment within outsourced pharmaceutical services offering robust opportunities for buyers.
CDMOs at a Glance
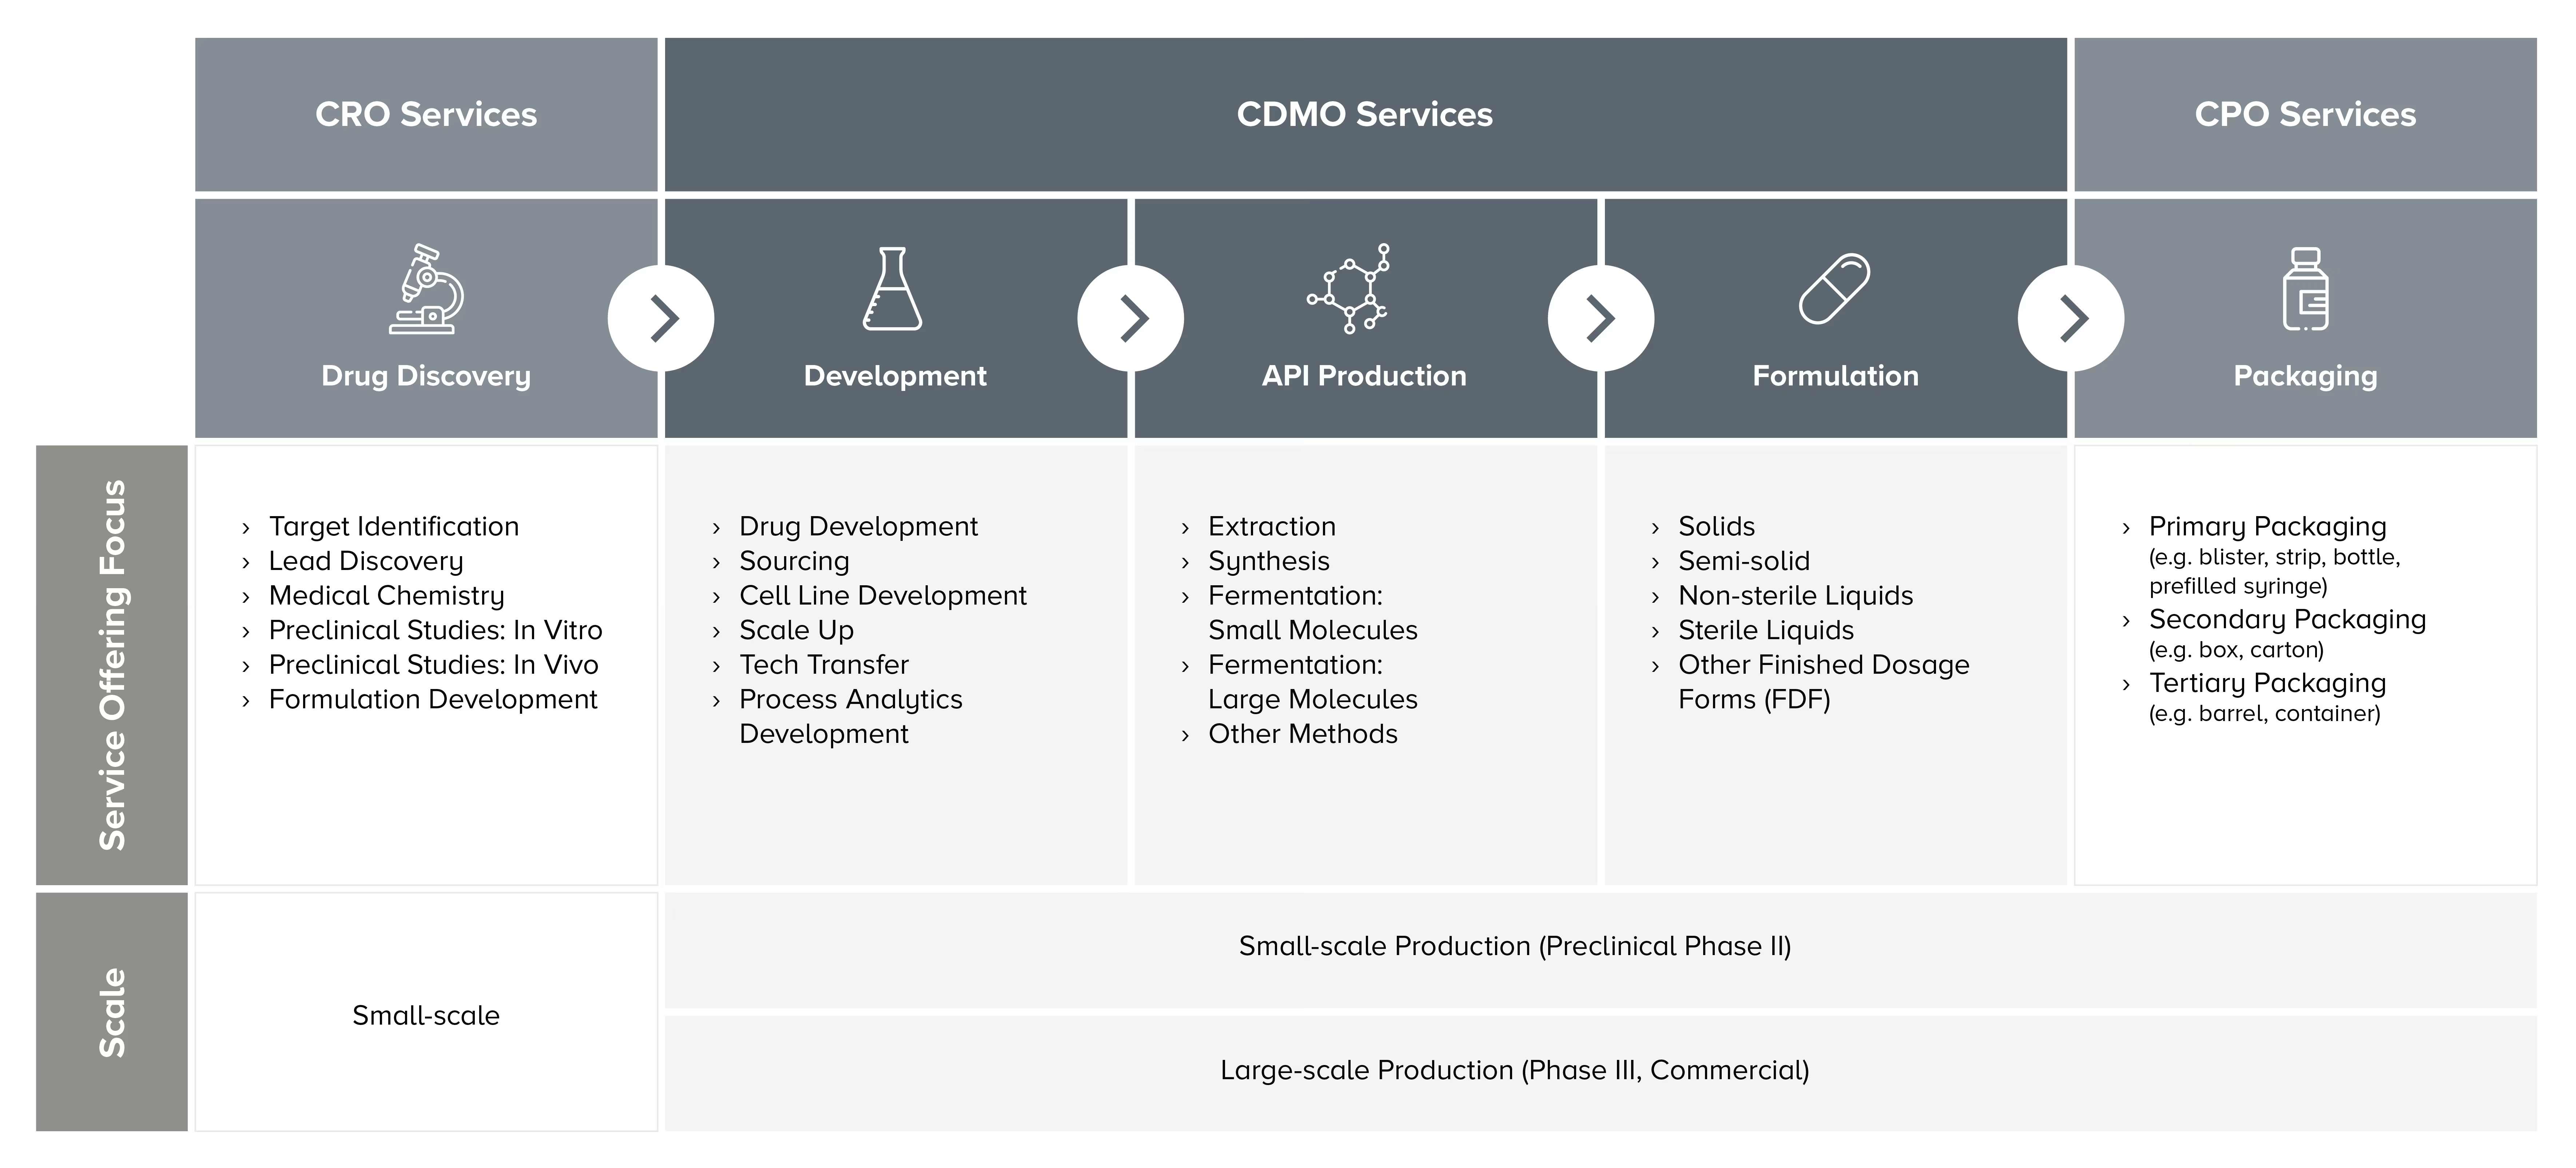
Contract development and manufacturing organizations (CDMOs) provide a range of services to pharmaceutical and biotech companies within the development and manufacturing cycle. These services can help customers manage their capacity requirements better and focus on core competencies such as drug discovery and commercialization.
Development outsourcing relationships are typically formed in pre-clinical and clinical trial stages of drug development, which strengthens the CDMO customer retention throughout the drug's lifecycle. The CDMO may produce the active pharmaceutical ingredients (APIs) for clinical studies and then, once approved, scale up to produce the API for commercial production to its strict standards. CDMOs also provide many valuable services beyond drug substance development, including sourcing, solid and specialty formulation development, and process analytics development.
Figure 1: Overview of the CDMO Value Chain
What Makes CDMOs Appealing to Investors?
CDMO segment growth is outpacing the wider pharmaceutical market as large-cap pharmaceutical companies and biotechs increasingly seek more flexible capacity and lower fixed costs. At a CAGR of 6.8%, the CDMO market is expected to grow to $117.3 billion by 2023.[1] With a current penetration of about 26%, the CDMO market shows substantial opportunity, especially when compared to other outsourced segments of the pharmaceutical industry, such as contract research outsourcing (CRO), which has a penetration of 45%.[2]
While the CDMO market is well-established, now is a time of particular growth for several reasons.
Pharma and biotech companies of all sizes are outsourcing
Larger companies are working to manage capacity and avoid the capital expenditure involved in building new manufacturing capacity. Flexible capacity, manufacturing footprint rationalization, lower fixed costs, and greater focus on higher-margin core business are all factors that drive increased outsourcing from large pharmaceutical manufacturers.
At the same time, the proportion of industry R&D outside of large-cap pharma is growing. Most small to mid-cap organizations—particularly biotech and specialty pharma businesses—are striving to be nimble and focus on drug discovery and commercialization rather than investing in development or manufacturing infrastructure.
Given the high fixed costs associated with manufacturing and development, as well as reliance on speed-to-market and efficient progress through clinical trials, these smaller companies benefit from outsourcing manufacturing and development services to CDMOs.
Ongoing shifts in medicine favor CDMOs
Pharmaceutical industry growth is being bolstered by several general trends, including the aging population and a corresponding increase in incidence rates for chronic and lifestyle diseases.
New drug development and improved diagnosis are also driving increased demand for medication.
"Priority-review therapies and other accelerated drugs are more likely to be contract manufactured than standard-review products,” says Scholl. "Upward trends in orphan drugs are positive signals for the CDMO sector. Small and midsized companies with priority review therapies represent a strong pipeline of business for CDMOs. Personalized medicine is also creating a shift in the industry. Manufacturing a personalized dose is much different than manufacturing a large batch, creating new opportunities for CDMOs."
Scholl adds that the increasing use of biologics—active drugs with bacterial and viral components, cancer treatments, or genetic therapies—also creates an opportunity for CDMOs. “Such products require a lengthier and more difficult commercialization process. They are more narrowly targeted, which makes optimizing smaller batch production critical. We've all witnessed firsthand how a new infectious disease can spur demand for biologic vaccines and fast-tracked manufacturing.”
COVID-19 highlighted supply chain vulnerability
During the pandemic, the U.S. CDMO sector was buoyed by the need for regional API and generic drug development since offshore sourcing wasn’t possible. Early drug shortages due to dependence on offshore manufacturing were rectified by onshore CDMOs. This prompted many pharmaceutical companies dependent on global manufacturing to seek ways to reduce their supply chain vulnerability by having multiple sourcing options.
Phlow, a pharmaceutical manufacturing company launched amidst the pandemic, is a great example of how the industry could be shifting. Recognizing that more than 80% of APIs are produced overseas, Phlow is working to actively accelerate the advanced manufacturing of affordable, high-quality essential medicines.
What to Look for in an Asset
There are multiple avenues for buyers and investors interested in the CDMO segment. Leading CDMOs may have differentiated technology, product formulation, or form factor capabilities. They could also differentiate through high-touch service, particularly by focusing on small and mid-cap customers early in the drug development process. End-to-end capabilities are attractive to customers of all sizes.
Differentiated technology/product capabilities
Scholl says CDMOs with differentiated high-value/high-demand formulation capabilities for products such as Metered Dose Inhalers (MDI), Biologic APIs, and High Potency Active Pharmaceutical Ingredients (HPAPI) can be great investments, although they are in highly competitive markets. These typically stable platforms can be strong foundations for moving into more niche opportunities, such as new biologic APIs. Product quality is the biggest customer priority in the higher-value, lower-demand space, and CDMOs that can achieve this create high barriers against competitors. CDMOs that produce cytotoxic pre-filled syringes are a great example of distinguished providers in this space.
CDMOs can also stand out through differentiated form factor capabilities. For example, sterile, inhalation, dissolvables, liquid capsules, topicals, injectables, and ophthalmics are highly specialized and higher value. Conversely, oral solid doses, vials, and semi-solids are widely available, making CDMOs in this space keenly focused on controlling costs and generating volume.
High-touch service providers
The clinical trial phase remains one of the most expensive and consequential hurdles for the drug development process. Delays or the inability to scale a trial because of product supply chain issues can cost pharmaceutical companies millions of dollars per day in future lost revenue due to the finite patent exclusivity period. Having a development partner that can deliver quality products on time is essential, and CDMOs that can reliably support early-stage development have an advantage.
Those involved early in the drug development life cycle also have the opportunity to add services such as discovery and commercialization and can therefore be end-to-end service providers. Typically, large CDMOs are more focused on providing either differentiated capabilities or end-to-end services for large-cap pharmaceutical customers. This leaves an opportunity for highly service-oriented CDMOs to provide end-to-end services for smaller biotechs and pharmas that may be underserved.
CDMOs typically benefit from in-house engineering groups that can design, fabricate, and install equipment. Highly skilled operations teams can deliver manufacturing services beyond the routine. Project management groups that can step into expanded roles to drive capital investment projects can widen options available to a client. Business development teams that can fill the pipeline are also critical.
Finding the Open Space
There are numerous ways to differentiate in the space, from building scientific expertise in biosimilars or biologics production or topical drug application to being a one-stop shop from concept through manufacturing, packaging and shipment. Many larger CDMOs are pursuing an end-to-end services model as their customers look to simplify outsourcing relationships, while smaller CDMOs work to provide end-to-end services for comparably sized biotech or specialty pharma companies.
Mikart, a company Harris Williams advised on its sale to Nautic Partners in 2018, offers a full range of integrated services, technology and support for the development, manufacturing and packaging of solid dose and non-sterile liquid pharmaceuticals. Mikart's broad range of capabilities includes formulation development, clinical trial supplies, regulatory filing support, analytical services, clinical manufacturing, commercial manufacturing, and packaging. Investment from Nautic Partners has helped Mikart become a recognized leader in its space.
Altasciences, for example, provides integrated, full-service solutions, including pre-clinical safety testing, clinical pharmacology and proof of concept, bioanalysis, and program management, all customizable to specific sponsor requirements. Harris Williams advised Altasciences on its sale to Novo Holdings in early 2021. The company, with roots in CRO services, has added multiple CDMO capabilities to scale and expand its end-to-end capabilities for smaller players in the industry, from pre-clinical trials to more scaled production.
Conclusion
The CDMO segment is highly fragmented, partially because of the variety of manufacturing and development services the pharmaceutical industry has historically needed, and partially due to the growing demand for services from outside of big pharma. No matter the driver, there is significant opportunity in this sector to build platforms that combine niche technologies or expand geographic capabilities.
See our Return on Innovation Series for more outsourced pharma services insights.
In addition to covering outsourced pharmaceutical services, the Harris Williams Healthcare & Life Sciences Group has deep expertise in a wide range of subsectors, from providers and payors to medical devices and healthcare IT.
For more information on outsourced pharmaceutical services and our experience in the space, please contact our professionals.
COVID-19: A catalyst for change in pharma outsourcing, RBC Capital Markets, https://www.rbccm.com/en/gib/healthcare/episode/covid19_a_catalyst_for_change#content-panel
ibid