

Article - November 4, 2024
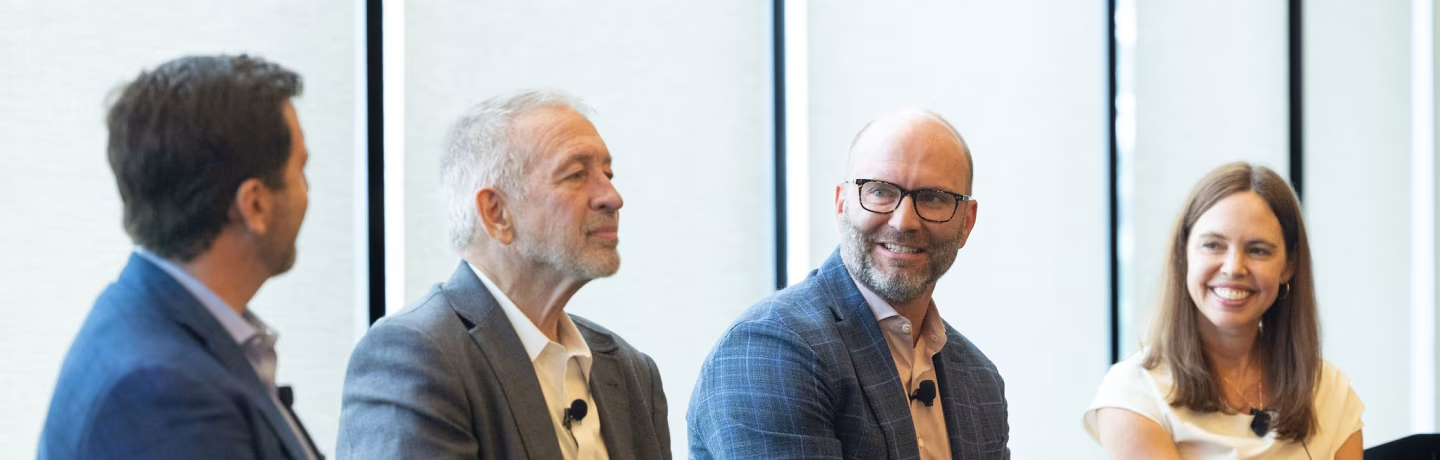
Harris Williams recently hosted its annual Consumer Health & Wellness Conference, bringing together industry executives, noted thought leaders, and private equity investors to network, share perspectives, and engage in relevant and timely sessions and panel discussions.
Below, senior professionals from our Consumer Group and Healthcare & Life Sciences Group highlight key insights into the current and future state of the consumer health and wellness space drawn from sessions, conversations, keynote speakers, and presenters at this year’s event.
Conference sessions:
Metrics That Matter: Quantifying Quality in Consumer Healthcare
In this lead-off session, Ryan Budlong, a group head and managing director in the Consumer Group, delved into what “quality” really means for consumer health and wellness businesses, all with the important caveat that there is no single metric that operators and investors should care about the most. “All the data works together to show a business’s momentum,” he says.
At the same time, Budlong highlighted a handful of measures that can have an outsized influence on acquisition multiples in the consumer health and wellness space. He referenced proprietary, quantitative support for key metrics that together show strong correlation to outsized exit valuations, including revenue growth, same-store sales, unit growth velocity, new unit ROI, and overall company scale. “It’s important to remember that metrics are only the output of a clear business strategy that provides real value to the consumer,” says Budlong.
Budlong also discussed several qualitative factors operators and investors should focus on, including industry growth, white space for expansion, and management quality: “These also boost multiples when they show above-average growth potential and market opportunity coupled with a team that’s prepared to go after that growth.”
Overall, Budlong emphasized that a combination of strong financial and operational performance across multiple dimensions drives the highest valuations in this dynamic and growing space. “Focus on building great businesses in great areas of consumer health and wellness, and your exit multiple will take care of itself,” he says.
Shooting for Glory: GLP-1s Generating Tailwinds
Michael Bennett, Chief Executive Officer, Formula Wellness
Phil Hagerman, Chairman and CEO, Forum Health
Stephanie Hu, Chief Executive Officer, Elase Med Spas
The advent of semaglutides like Ozempic and Wegovy is influencing many areas of consumer healthcare and beyond. This panel discussion highlighted the impacts of this trend on businesses today and going forward.
“Consumers are being bombarded with advertisements for GLP-1 products and the variety of options for uses and purchase options. It is very important that they seek professional guidance on using them safely and effectively,” says Corey Benjamin, a managing director in the Consumer Group. “Med spas are well positioned to play this important role.”
Panelists pointed out that while GLP-1s are among the most effective pharmacological weight loss treatments to ever emerge, successfully reaping their benefits requires lifestyle changes and complementary services. "Our panel members stressed the importance of working with each individual client to meet their unique health and weight objectives,” says Benjamin. “GLP-1s can jump-start significant health and wellness improvements, but only when used as part of a thoughtful and customized regimen aimed at long-term behavioral change, including diet, exercise, sleep, and mental and emotional health.”
Along those lines, the providers on our panel emphasized developing comprehensive, personalized patient approaches rather than just providing GLP-1 prescriptions. In many instances, these plans include hormone balance, nutrition, and lifestyle changes. Similarly, the panel discussed how GLP-1 usage has led to increased demand for complementary post-weight loss aesthetic services like injectables, skin tightening, and body contouring at med spas and wellness clinics.
While excited about the potential of GLP-1s to improve health and wellness, panelists shared some concerns about the rise of unregulated direct-to-consumer compounded GLP-1 medications, which may not provide the same level of medical oversight and safety. “This is another reason leading aesthetics and wellness providers are poised to play an important role going forward,” says Benjamin. “They can ensure that patients achieve the benefits of a clinically rigorous, whole-health approach to weight loss.”
Looking forward, the promise of GLP-1s and the central role of aesthetics and wellness providers in their safe and effective use bodes well for the continued growth of businesses in the space. “Leading providers are helping consumers improve their wellbeing via comprehensive services and thoughtful guidance,” concludes Benjamin. “That’s a formula for healthier consumers, businesses, and investors.”
The HSR and State Regulatory Blueprint: Decoding the Latest Updates
Mike Schaper, Partner, Debevoise & Plimpton
Kim Le, Counsel, Debevoise & Plimpton
Our third session of the day was a deep dive into the Hart-Scott-Rodino (HSR) Act, a set of amendments to United States anti-trust laws that requires companies to file premerger notifications with the Federal Trade Commission and the Department of Justice. In October 2024 the FTC finalized these changes, which are set to take effect in early 2025 and will increase the time, effort, and cost associated with these filings.
Schaper and Le highlighted several significant changes to the HSR filing process, including expanded data and document requirements. This includes requiring companies to describe in greater detail how they compete with each other and provide regulators with more internal documents. While less cumbersome for filers than initial drafts of the proposed changes, these changes will make the process more burdensome and time-consuming. In addition to greater federal oversight, consumer health and wellness businesses are also now subject to increased state-level regulation, with several states implementing notification or review and approval filing requirements that can extend the dealmaking timeline. Overall, regulators intend for these changes to help them spot problematic transactions more readily, and the shifts align more closely with the European regulatory approach to M&A.
“Buyers and sellers should plan on building in extra time for HSR-driven work, including collecting the required information and working with advisors to understand potential issues,” says Benjamin. “It’s a good idea to involve antitrust counsel early in the deal process, and to err on the side of caution and preparedness.”
Cyber Threats: Navigating Risky Terrain
Robert Booker, Chief Strategy Officer, HITRUST
Our discussion of the dynamic cybersecurity threat environment faced by healthcare providers highlighted proven approaches to safeguarding patient well-being and minimizing liability risks. “Unfortunately, healthcare providers are increasingly becoming targets of cyberattacks, particularly ransomware and cyberextortion,” says Dan Linsalata, a managing director in the Healthcare & Life Sciences Group.
This trend has accelerated over the past 18-24 months, with healthcare organizations being disproportionately impacted due to the sensitivity of patient data and the disruption an attack can have on care delivery. “We discussed how disrupting healthcare providers’ operations can create a crisis and gain notoriety for the attackers,” he says. “Providers are also more likely to pay ransoms so they can quickly get back online and treat patients.”
The threat environment is evolving rapidly, with criminals becoming less discriminating in terms of who they target. Hackers are also increasingly exploiting vulnerabilities in third-party solutions and the broader healthcare technology ecosystem. Specifically, Linsalata and Booker discussed how attackers are targeting any organization with patient data that needs to be protected, not just large health systems.
And, while regulations like HIPAA exist, that guidance is often outdated and lacks clarity on what constitutes sufficient security. Linsalata and Booker discussed the need for more comprehensive security frameworks that provide a clear path for providers to mature their security capabilities and achieve a higher level of assurance.
Key elements of such a framework include understanding the full scope and dependencies of a business’s technology systems. “The healthcare ecosystem is highly interconnected,” says Linsalata. “Weak integration points between providers, third-party vendors, software tools, and hosting providers, along with other vulnerabilities, can compromise the whole network.”
It’s also critical for healthcare providers to address common blind spots, including not knowing the full scope and location of IT systems, failing to implement basic security controls like strong passwords and two-factor authentication, and not checking security maturity on an ongoing basis. Overall, adopting a continuous improvement mindset to stay ahead of evolving threats is vital. This is often best handled by leveraging security capabilities from cloud providers and other vendors, who are already keeping up with these shifts and focus exclusively on IT security.
“While it’s not a new phenomenon, it’s disheartening to see cyber criminals targeting healthcare providers,” says Linsalata. “The good news is that most providers can significantly bolster their security by taking some basic steps, and there’s a large ecosystem of experts ready to help fortify and maintain those defenses as the environment continues to shift.”
Scaling Success: Opening Diverse Exit Paths
In our final session of the day, senior professionals from Harris Williams discussed the fundamental rationale behind building multisite healthcare companies, exploring key considerations for building a scaled business that maximizes investor interest and unlocks viable exit opportunities.
More specifically, the session focused on the evolution of physician practice management (PPM) businesses, highlighting the challenges they have faced and the opportunities ahead.
“The PPM model remains critical, with growing demand from physicians and patients for the services it provides, such as operational support, access to resources, and, in certain subsectors, a path to value-based care,” says Geoff Smith, a group head and managing director in the Healthcare & Life Sciences Group. “Independent medical practices are facing increasing pressures, such as regulatory and billing challenges, that are making it difficult for them to operate independently. This is driving them to seek alternatives to the traditional independent practice model, and the PPM model has never been more relevant or needed.”
“Physicians, especially younger ones, want different things compared to the previous generation,” says Andy Dixon, a managing director in the Healthcare & Life Sciences Group. “They’re looking for work environments and models that better fit their preferences, which the PPM model is designed to provide.”
In particular, Dixon and Smith note that factors like rising physician burnout and care moving away from expensive hospital settings are creating more demand for the services and value proposition that the PPM model can deliver. They also note that, while varying by subsector, the PPM model in general continues to mature. Its early focus on M&A-driven growth is shifting to more sophisticated approaches to organic growth, provider alignment, infrastructure development, and developing the capabilities that may eventually enable a shift toward value-based care for a broader portion of the U.S. healthcare system.
This evolution is part of the reason why, despite recent macroeconomic headwinds, the PPM model has shown resilience and M&A activity is expected to pick up. That’s especially true for high-quality businesses that can articulate a path to value-based care, says Smith: “Articulating a credible plan for transitioning to value-based care models will be an important differentiator for businesses looking to position themselves for strong exits or acquisitions.”
In terms of alternatives to M&A, Richard Siegel, a managing director in the Harris Williams Private Capital Advisory Group, noted a growing range of strategies, including minority investments, structured equity, and continuation vehicles.
“These alternative options are gaining momentum as the traditional majority sale exit has become more challenging in the current PPM market environment,” says Siegel. “They can all provide liquidity and growth capital, as well as give investors more ways to participate in the long-term growth of this market."
“The drivers of the physician practice management model will only get stronger,” concludes Smith. “It plays a critical role in the healthcare ecosystem that can’t be addressed by any other model, and fits with where physicians are going. We’re looking forward to the growth and innovation to come.”
Upside Ahead
The consumer health and wellness space remains of great interest to investors, with resilient consumer demand for services and products related to health, wellness, fitness, sleep, and mindfulness. Buyers are prioritizing best-in-class businesses with consistent and strong performance, a proven ability to recruit and retain talent, strong clinical quality, and a clear roadmap to growth.
“This industry has seen plenty of change and a few challenges in recent quarters, but the fundamentals are healthy,” says Benjamin. “Consumer health and wellness providers sit at the intersection of numerous powerful tailwinds, and demand for services is strong. We see significant upside looking ahead to 2025 and beyond.”
To discuss M&A opportunities across the consumer health and wellness space in detail, please contact our senior professionals.